
Construction Company Exit
2.5-4.5x EBITDA Valuation | Strong Backlog +20-30% | Certifications +15-25% | 2025 Market Guide
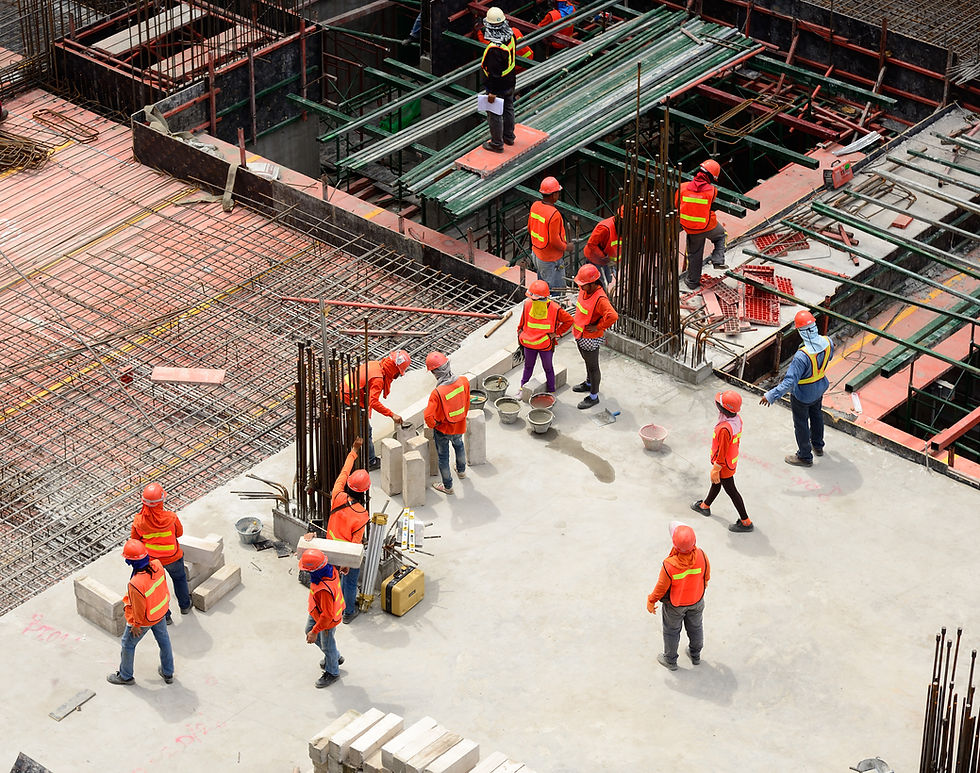
Construction companies attract strategic buyers and PE firms seeking consolidation and operational improvement opportunities. Valuation depends heavily on project pipeline (backlog), skilled workforce, and certifications (Health & Safety, ISO). Companies with 12-18 months of visible backlog and strong skilled workforce command 3.5-4.5x EBITDA. Project-dependent businesses with variable backlog see 2.5-3.5x. Supply chain resilience and health/safety record are critical differentiators.
Valuation range: 2.5-4.5x EBITDA depending on backlog visibility and workforce quality
Strong backlog (12-18 months): +20-30% valuation premium (revenue visibility)
Certifications & H&S record: ISO, ISO 45001 certifications = +15-25% premium
Skilled workforce: Trained, stable crew = +15-20% premium vs subcontractor-dependent model
Timeline: 14-18 weeks due to complex due diligence on contracts and project delivery
Construction Valuation Formula: EBITDA × Base Multiple (2.5-4.5x) + Backlog Premium (up to +30% for 12+ months visible work) + Workforce Premium (up to +20% for skilled direct employees) + Certification Premium (up to +25% for comprehensive H&S/ISO) = Final valuation. Project pipeline visibility is often more important than historical EBITDA.
Construction Valuation by Sector
Sector | Multiple | Key Differentiator | Buyer Type |
General Contracting | 2.5-3.5x EBITDA | Project pipeline, customer relationships | Larger contractor, PE consolidator |
Specialist/Trade | 3-4x EBITDA | Skilled workforce, certification, recurring projects | Strategic contractor, PE |
Infrastructure/Public Works | 3.5-4.5x EBITDA | Long-term contracts, backlog, public sector relationships | Major contractor, PE infrastructure fund |
Plant Hire/Equipment | 3-4x EBITDA | Fleet condition, maintenance, utilization rates | Equipment consolidator, PE |
Key Construction Valuation Drivers
Project Backlog (±30%) - 12-18 months visible work = premium. <3 months = major discount
Workforce Stability (±20%) - Direct employees vs subcontractors. Skilled, trained team = premium
Certifications & H&S (±15-25%) - ISO 9001, ISO 45001, Safe-Contractor rating = premium
Customer Concentration (-25% to 0%) - Diversified customer base = premium. Single customer >50% = discount
Asset Base (±15%) - Modern equipment, well-maintained = premium. Depreciated assets = discount/capex concern
Margins (±10-15%) - Consistent 10%+ EBITDA margin = premium. Declining margins = concern
Pre-Exit Construction Optimization
Build project pipeline (18-24 months pre-exit): Secure 12-18 months of backlog through customer relationships and bids
Achieve key certifications: ISO 9001, ISO 45001, Safe-Contractor status. Each certification adds 5-15% value
Invest in skilled workforce: Direct employee team vs subcontractors. Training, retention, safety culture
Upgrade equipment/fleet: Modern, well-maintained equipment indicates operational quality
Diversify customer base: Reduce single customer concentration below 30%
Document H&S record: Clean safety record, incident-free history demonstrates risk management capability
Construction Exit Red Flags
❌ Thin project backlog (<3 months) = major revenue visibility risk, 25-35% discount
❌ Safety incidents/poor H&S record = buyer risk concern, significant discount or deal-breaker
❌ Single customer >50% = project loss risk, 20-30% discount
❌ Subcontractor-dependent model = workforce quality risk, 15-25% discount
❌ Aging equipment/fleet = capex needs, 15-20% discount or deduction from price
Real Example: Specialist Trade Contractor Exit
Case Study: £1.8M Electrical Contractor Sale
Business Profile: 45-person commercial electrical contractor, £600k EBITDA, 14-month backlog, ISO 9001 + ISO 45001 certified, direct employees (90% of work), diverse customer base (top 3 = 35% of work)
Valuation: 3.5x base multiple = £2.1M
+25% backlog premium (14-month visibility)
+20% workforce premium (direct employee model)
+20% certification premium (ISO 9001 + ISO 45001)
-10% customer concentration (top 3 = 35%)
= 4.45x final multiple = £2.67M estimate
Actual Sale: Larger electrical contractor at 4.2x EBITDA = £2.52M
Results: Strong backlog, skilled workforce, and certifications justified significant premium. 14-month backlog reduced buyer pipeline risk concerns
Timeline: 15 weeks (extended contract audit and customer verification)
Construction Exit Timeline
Phase | Duration | Activities |
Preparation (Pipeline & Compliance) | 3-4 weeks | Backlog audit, contract review, certification documentation, H&S record compilation |
Buyer Engagement | 3-4 weeks | Larger contractors, PE construction funds, strategic acquirers |
Due Diligence (Project & Compliance Focus) | 5-6 weeks | Project contract review, customer verification, H&S/certification audit, workforce assessment |
Negotiation | 2-3 weeks | Project transition terms, workforce retention, backlog commitment verification |
Completion | 2 weeks | Legal documentation, project handover, team integration planning |
Total | 14-18 weeks |
Ready to sell your construction company?
Build a strong project backlog, invest in your skilled workforce, and maintain certifications. Construction companies achieve 3.5-4.5x EBITDA multiples based on pipeline visibility and operational excellence.


Comments